"*" indicates required fields
We're committed to your privacy. For more information, check out our Privacy Policy.
On Behalf of MacGregor Lyon
Quick Summary
For many Georgia business owners, "LLC vs. S-corp" is not really a clean apples-to-apples question. An LLC is a legal entity formed under state law. An S corporation is a federal tax status that an eligible corporation, or an eligible LLC treated as a corporation for tax purposes, can elect. So the practical decision is often whether to keep the default LLC tax treatment, have an LLC elect S-corp taxation, or use a corporation that elects S-corp status. The right answer depends on ownership plans, compensation, tax structure, administrative tolerance, and how formal the business needs to be.
Many Atlanta business owners ask whether they should be an LLC or an S-corp as if they are choosing between two completely different species.
That is where the confusion starts.
The more accurate first principle is this: an LLC is a business entity. An S corporation is a tax election available only to eligible entities. Once that clicks, the rest of the conversation gets much more practical.
First, Separate the Legal Choice From the Tax Choice
Under Georgia law, you can form an LLC or a corporation. Those choices affect governance, ownership mechanics, and how the business is organized.
At the federal tax level, an eligible corporation can elect S-corporation status. An eligible LLC can also elect to be treated as a corporation and then elect S-corporation status. That is why many owners who say they want to "be an S-corp" are really asking whether they should keep the LLC but change the tax treatment.
That distinction matters because owners sometimes make a tax decision without understanding the governance and documentation work that should go with it.
What an LLC Usually Gives a Small Business
An LLC is often attractive because it is flexible.
For many owner-managed businesses, an LLC can make sense when the owners want:
- limited liability
- flexible internal governance
- fewer corporate-formality expectations than a corporation
- pass-through treatment by default for federal tax purposes
- an operating agreement that can be tailored to the actual ownership deal
That flexibility is one reason so many small businesses start there. But the flexibility only helps if the business actually uses it. A Georgia LLC with no serious operating agreement can still create disputes about control, distributions, exits, and deadlock. That is why MacGregor Lyon’s article on why every Atlanta small business needs a written operating agreement remains relevant even for owners who think the structure decision is already finished.
What People Usually Mean When They Want S-Corp Treatment
In most small-business conversations, the S-corp appeal is tax-related.
Owners are usually asking whether the business has reached a point where electing S-corporation taxation could make sense compared with staying in the default LLC tax regime. That can raise issues around payroll, owner compensation, distributions, recordkeeping, and tax coordination with the company’s CPA.
The federal rules also come with eligibility requirements. S corporations must meet shareholder and stock restrictions, and shareholder-employees who perform services generally need reasonable compensation before non-wage distributions are made.
That is where the conversation stops being just "tax savings." The election can create real compliance and payroll discipline that some owners underestimate at the start.
Georgia Adds Its Own Practical Layer
Georgia business owners also need to think about the state-side filing and tax picture.
The entity still has to be properly formed and maintained with the Georgia Secretary of State. Annual registration is still required for LLCs and corporations. On the tax side, Georgia has separate corporate tax guidance for S corporations, and Georgia recognizes S-corporation filing status subject to its own rules, including shareholder-consent issues for some nonresident owners.
In other words, the election is not just a box on a federal form. It has ripple effects for how the business runs and reports.
When Staying an LLC Often Makes More Sense
Keeping the default LLC treatment often makes sense when:
- the business is early-stage or not consistently profitable yet
- the owners want simpler administration
- compensation is still volatile
- there are special allocation or ownership-planning needs
- the business is still figuring out who the long-term owners are
This can also make sense for companies that need legal flexibility first and tax optimization second. For some owners, forcing more complexity into the entity before the business is ready for it solves the wrong problem.
When an LLC With an S-Corp Election May Make More Sense
An LLC that elects S-corp taxation may make sense when:
- the business has steadier profit
- owner compensation can be run through payroll in a defensible way
- the owners want LLC governance but are exploring a different tax posture
- the administrative cost and discipline are acceptable
This is often the middle path people are actually looking for. They do not want to abandon the LLC structure, but they do want to revisit how the business is taxed.
That said, this only works well when the lawyer and CPA are not working in separate silos. The entity documents, ownership structure, and compensation planning should fit together.
When a Corporation Itself May Be the Better Fit
Sometimes the better answer is not "LLC plus election." It is using a corporation because the business expects outside investment, more formal equity planning, or a structure that already aligns with how the owners want to issue and manage stock.
That is especially true if the company expects founder changes, option planning, or investor-facing documentation that benefits from a corporation-first framework. The point is not that corporations are better across the board. It is that growth plans, investor expectations, and administrative preferences can justify the added formality.
The Legal Question and the Tax Question Should Happen Together
This is where owners often lose time.
They ask a CPA whether the S election might save taxes, but do not ask whether the entity documents, ownership arrangements, and compensation setup are ready for that election. Or they ask a lawyer to form an LLC without discussing how the owners plan to pay themselves once the business grows.
MacGregor Lyon’s role as outside general counsel fits this gap well because the structure question often touches multiple documents at once:
- entity formation
- operating agreement or bylaws
- owner compensation and distributions
- service agreements or employment agreements for owner-operators
- future sale or succession planning
That is also why some business owners need both legal and accounting guidance. The business-structure conversation is not an attorney-versus-CPA issue. It is frequently an attorney-and-CPA issue, with each piece solving a different part of the problem.
Practical Questions to Ask Before You Change Anything
Before deciding, ask:
- Am I choosing a legal structure, a tax election, or both?
- Is the business profitable enough to justify the added payroll and compliance work?
- Will owner compensation be handled in a way that matches IRS expectations?
- Do the current ownership documents actually support the structure I think I have?
- Is the business likely to bring in investors, add owners, or sell in the foreseeable future?
Those questions usually produce a better answer than chasing the structure someone on the internet said is "best."
The Bottom Line
For many Georgia businesses, the real question is not LLC versus S-corp in the abstract. It is whether the company’s legal structure, tax treatment, and future plans are aligned well enough to support growth without creating extra friction.
If you are revisiting your entity choice, owner compensation, or operating agreement, it is worth getting the legal and business side of the decision lined up before you file anything. MacGregor Lyon advises Atlanta business owners on entity formation, operating agreements, contracts, and practical outside-general-counsel planning. Schedule a free consultation with Glenn. Call (404) 688-5964 or visit macgregorlyon.com.
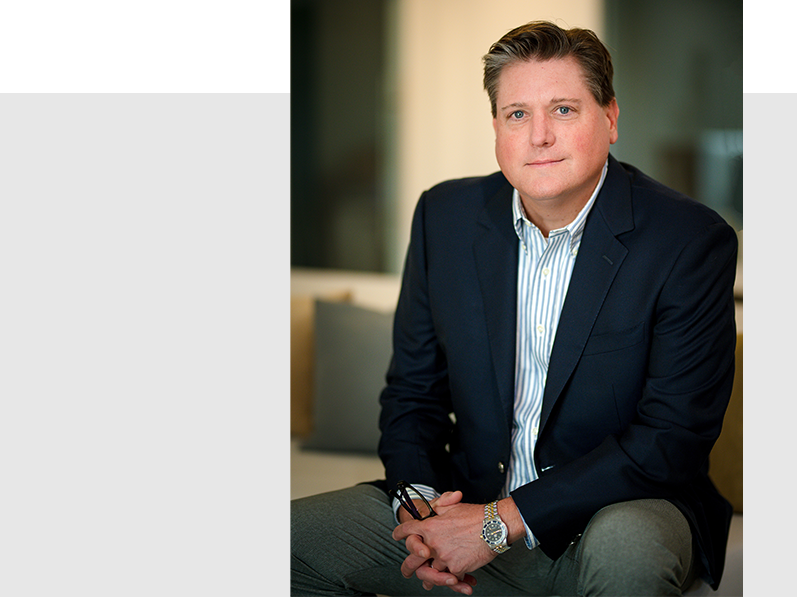
On Behalf of MacGregor Lyon
Principal Partner
Glenn M. Lyon is a distinguished business attorney recognized for his exemplary service to small and medium-sized, privately-held businesses, and start-up companies.
Employment Agreements for Georgia Small Businesses: What Every Hiring Contract Should Include